Price-to-Book (P/B) and Price-to-Sales (P/S): Alternative Valuation Ratios
When P/E falls short for banks or high-growth names, P/B and P/S offer clearer alternatives. Here’s how to use them, what they miss, and why the USD multiple on your screen is not the same as the AUD cost base in your tax working.
Investing 101 Quartet No. 3 — Specialised Funds & Corporate Actions
Week 11: The Metric
Two weeks ago the question was how to express a targeted view on a sector or structural trend without picking individual stocks. Sector funds and thematic ETFs let you do that in a single trade, sized as a modest satellite around a broad core holding.
Last week the question was what actually changes in a stock split or reverse split. Share count and price move in opposite directions; your ownership percentage and the company’s total value do not. For Australian holders the practical points were clear: a split is not a CGT event, and the cost base is simply reallocated across the new share count.
This week the question is how you value a company when the price-to-earnings ratio is less useful or actively misleading. P/E asks how much you are paying for a dollar of earnings. It works for stable, profitable businesses with clean numbers. It works less well for banks whose earnings swing with provisions, and it collapses for high-growth companies that are not yet profitable. Price-to-book and price-to-sales are the two most common alternatives. They are still ratios, not verdicts.
Price-to-Book: What the Balance Sheet Says You Own
Book value is the accounting residual: total assets minus total liabilities, usually expressed per share after preferred stock is removed. Price-to-book divides the current share price by that book value per share (or market capitalisation by shareholders’ equity).
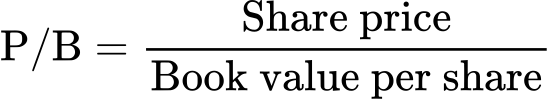
A P/B of 1.0 means the market is pricing the company at the accounting value of its net assets. Below 1.0 the market is applying a discount; above 1.0 it is applying a premium.
The ratio is most commonly used for banks and other financials. Reported earnings can be noisy because of credit provisions, trading gains or losses, and the timing of interest-rate moves. Book value moves more slowly and is the capital base regulators actually watch. A bank that consistently earns a high return on equity (ROE) can justify a premium to book; a bank that earns a low or volatile ROE usually trades at a discount.
As at mid-November 2026, JPMorgan Chase was trading around 2.5–2.6 times book value per share. Book value per share stood at $132.30 at the end of the September quarter; tangible book value per share was $112.64. Return on equity sat in the high teens. That is a clear premium to most large US regional banks, which more often trade between 1.0 and 1.6 times book. The premium reflects scale, diversification and a long track record of earning above the cost of capital. It is not automatic. If ROE were to fall persistently toward the low teens or below, the multiple would be harder to defend. Many bank investors focus on price-to-tangible-book rather than plain P/B, because it strips out goodwill and other intangibles that can inflate the equity figure.
P/B is weaker for asset-light businesses. Software platforms and many technology companies carry relatively little tangible book value relative to their market capitalisation. A high P/B in those cases often simply means the balance sheet does not capture the economic value of the franchise. Large goodwill balances from past acquisitions, or aggressive share buybacks that shrink equity without changing the underlying business, can also distort the number.
Price-to-Sales: When Earnings Are Not the Right Denominator
Price-to-sales divides market capitalisation by trailing twelve-month revenue (or share price by revenue per share).
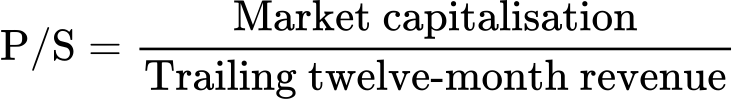
It is useful when a company has little or no current earnings, either because it is still investing heavily for growth or because it is early in its life as a public company. Sales are almost always positive and tend to be less volatile than earnings in the short term.
The ratio does not tell you whether those sales are profitable or likely to become so. Consider two software businesses, both trading at 15 times trailing sales:
- Company A has 75 % gross margins, 40 % revenue growth, and strong net revenue retention. A large share of each additional dollar of sales drops toward future profit.
- Company B has 40 % gross margins, 15 % revenue growth, and high customer churn. Far less of each sales dollar becomes profit, and growth is slower.
Both show the same P/S on a screen. Company A can more readily support the multiple; Company B is more likely to disappoint if the growth or margins fail to improve. Growth rate, margin structure and capital intensity all matter.
Recent readings illustrate the range. Nvidia has traded in the low-to-mid teens on trailing sales for much of 2026 after a period of far higher multiples. Palantir has spent extended stretches above 50 times trailing sales. Both numbers describe what the market is currently willing to pay for a dollar of revenue; neither is a prediction that the growth rate will continue or that the business will convert that revenue into free cash flow at an attractive rate.
P/S is also sensitive to one-off revenue recognition or to businesses with very low incremental margins. A retailer or commodity producer trading at a low P/S may still be expensive once you adjust for the capital required to generate each additional dollar of sales. Conversely, a high-growth software business trading at an elevated P/S can look more reasonable on a forward basis if analysts expect revenue to compound quickly and margins to expand.
A Simple Comparison
| Situation | Prefer | Why | Watch for |
|---|---|---|---|
| Stable, profitable industrial or consumer business | P/E (trailing and forward) | Earnings are the clearest link to cash | One-off items, capital intensity |
| Bank or asset-heavy financial | P/B (or price-to-tangible-book) | Book value is the regulatory and economic capital base | ROE sustainability, credit cycle, goodwill |
| High-growth or currently unprofitable tech / biotech | P/S | Sales are positive and growing | Margin trajectory, retention, capital needs |
| Mixed or unclear | Both, plus free cash flow | Cross-check the story | Consistency between the ratios and the cash flow statement |
The Australian Layer
These ratios are calculated on US-dollar figures. The price that enters your Australian tax working is the AUD amount you actually paid on the day of purchase, converted at the spot rate that day. A subsequent move in the AUD/USD rate changes the AUD cost base of that parcel without changing the USD multiple you see on a US screen. The multiple and the exchange rate are separate.
Two further practical points for Australian holders:
- Book value and revenue are reported in USD. Any screen P/B or P/S is therefore a USD multiple. When you later convert the position back for tax purposes, currency movement sits on top of that multiple; it does not alter the ratio itself.
- Aggressive share buybacks can lift P/B by shrinking the equity denominator, and large share-based compensation can increase the share count used in per-share calculations. Neither changes the AUD cost base of the shares you already own, but both can make the multiple you see on a US screen look different from the economic position you actually hold.
Neither P/B nor P/S creates a tax event. They are inputs to a decision, not triggers. Brokers and the ATO treat the underlying shareholding the same way whether you arrived at the decision by looking at book value, sales, earnings or something else. What matters for CGT is the acquisition date, the AUD cost base, and the AUD proceeds when you eventually sell. Pure growth names that pay no dividend also offer no US withholding tax to reclaim — a practical difference from dividend-paying banks or mature industrials.
A Practical Checklist
- Have you calculated both the trailing and any available forward version of the ratio, and noted the exact source and date of the denominator?
- For a P/B, does the company earn a return on equity that has historically supported a premium (or discount) to book, and is that ROE likely to persist? Have you checked tangible book if goodwill is material?
- For a P/S, what growth rate and margin structure are required for the current multiple to look reasonable in three to five years? Is free cash flow expected to follow revenue?
- Have you compared the ratio to the company’s own history and to a small set of true peers, and separated any AUD/USD currency overlay from the USD multiple itself?
Price-to-book and price-to-sales expand the toolkit for the cases where earnings are noisy or absent. They do not replace the need to understand the business, the competitive position, or the cash the business actually generates. They remain ratios. The work is in deciding whether the number in front of you is consistent with the economics of the company you are looking at.
Data Sources:
- JPMorgan Chase third-quarter 2026 earnings materials and Form 10-Q (book value per share $132.30 and tangible book value per share $112.64 as at 30 September 2026; ROE in the high teens).
- Public market data for mid-November 2026 prices and multiples (JPM P/B range ~2.5–2.6×; Nvidia trailing P/S in the low-to-mid teens; Palantir trailing P/S extended periods above 50×).
- ATO guidance on capital gains tax for foreign shares and cost-base calculation (currency conversion on acquisition date; no CGT event on a pure valuation-ratio assessment).
- Standard broker practice for US-listed securities held by Australian investors (automatic adjustment of share count and cost base on corporate actions; no automatic tax event from a change in a published multiple).
Wall St. Down Under | Australia
Subscribe | wallstdownunder.com.au
Disclaimer: Wall St. Down Under is an independent financial newsletter for informational and educational purposes only. Nothing published here constitutes financial advice, a recommendation to buy or sell any security, or a solicitation of any investment decision. Always do your own research and consult a licensed financial adviser before making investment decisions. Australian investors should consider their own financial situation, objectives, and risk tolerance. Past performance is not indicative of future results.